Imagine your bank being able to resolve any client’s query instantly, identify scams, and save costs on operations while not touching existing software.
This becomes achievable with the help of generative AI.
By using the technology to improve operational efficiency and customer experience in different areas such as customer support or lending, banks see the benefits.
The article covers all the aspects of the use of the technology in banks: benefits, examples, challenges, and ways to pick the right platform.
What Is Generative AI in Banking?
Start with what came before. Old banking algorithms look backward. They take past numbers, do one narrow job, and stop.
They compute a credit score or flag an odd debit. Some run phone menus that only catch a few set keywords. Press 1, press 2, give up.
The Generative AI technology in banking handles the messy aspects of the process. These include scanned loan forms, analysts’ calls, policy guides, and how people talk.
If there is something unusual about the card transaction, the old system would raise an alert and walk away. However, the new one will document the case for the fraud department and notify the cardholder.

Legacy tools live in silos, and that’s the real problem. Generative AI in banking ties the front, middle, and back offices together. Up front, it runs voice agents and gives staff a live copilot. In the middle, it speeds up risk reviews, anti-money laundering checks, and audits. In the back, it reads commercial loan packages and helps engineers clean up aging code.
How Does Generative AI Work in Banking?
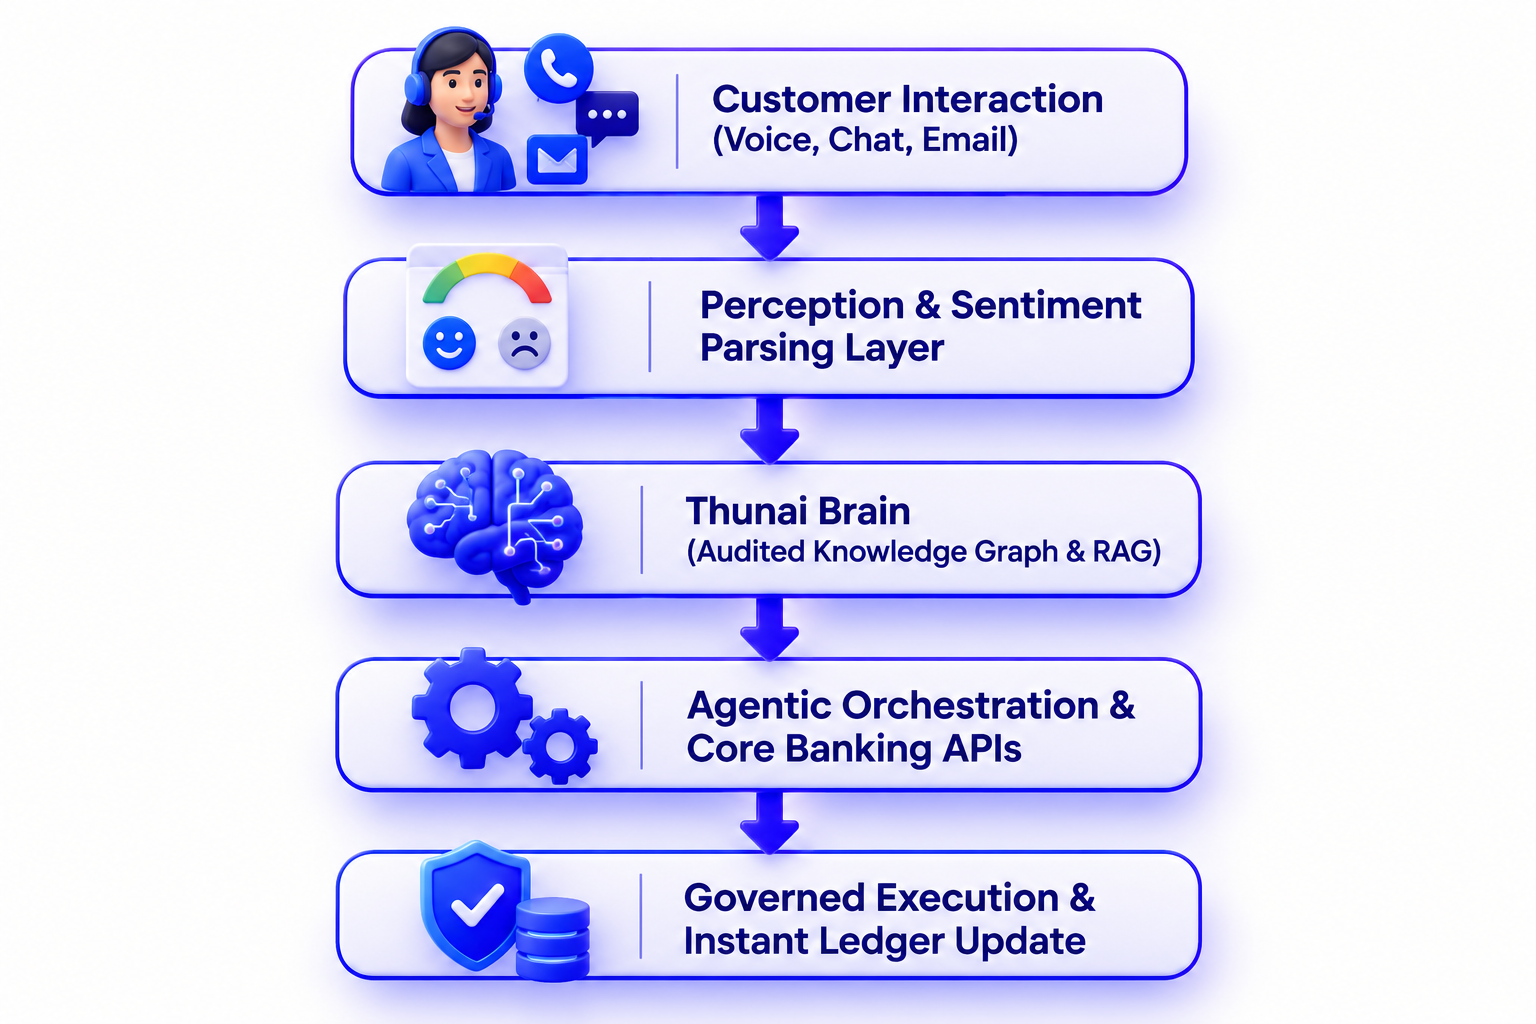
What’s going on under the hood? Running generative AI in banking takes a connected stack, because the language models have to plug into core banking records and security controls. Most production platforms use five layers:
- Perception and Channel Layer: Catches every customer touchpoint, from phone and web chat to mobile apps and email. It turns speech into text and tracks intent and mood as the talk goes on.
- Enterprise Knowledge Layer: Soaks up policy files, fee schedules, and product guides. Platforms like Thunai Brain connect to document stores and clear out rules that clash across departments.
- Agentic Orchestration Layer: Weighs each request against financial ontologies, then makes the call. Can the AI settle this alone, or does a person step in?
- Integration Layer Protocol: Runs on open standards like Model Context Protocol. Secure APIs connect it to core ledgers, CRM, and ticketing systems.
Accuracy is the primary concern, but retrieval-augmented generation will always help resolve that. Generative AI in banking is used to access facts from confirmed sources such as documents within the bank and not from open sources.
For example, Thunai Brain links knowledge through internal systems and reduces errors and hallucinations of AI by 95%. Add specialized AI agents for banking and finance, and the system can check balances, update records, and lock a stolen card.
Want to see how live customer context reaches backend data? Read our analysis of AI personalization in customer service.
Benefits of Generative AI in Banking
The benefits of generative AI in banking show up in customer service, compliance, and the back office.
- Support is the easy win.AI Generators in Banking may respond to many queries without any human intervention. The virtual agents are capable of checking the balance, providing transaction details, and requesting replacement of debit cards.
- Banks using them deflect up to 80% of routine tickets. Our guide on AI ticket deflection for banks has the full breakdown.
- Human agents benefit too. On a live call, agent assist software listens, finds the right policy, and puts next steps on the screen.
- Average Handle Time falls by 42% to 66%. Time spent digging for internal answers drops by 95%. Then the customer hangs up, and the system writes the notes and updates CRM fields in 0.8 seconds. That saves 10 to 15 minutes of paperwork per call.
Our overview of customer service automation systems shows how these workflows run.
Generative AI for Banks - Adoption Trends and Market Growth
Adoption of generative AI in banking has moved fast. Pilots turned into daily operations in just a few years.
- Why the rush? Banks invest in generative AI in banking since they need long-term efficiency. Only 5% of banking technology executives had active solutions in 2024, while 37% were still planning pilots.
- In 2025, the wider finance industry reached 59%. Production use in retail and commercial banks then climbed from 29.9% in 2025 to 50.4% in 2026. Today, 77% of institutions have launched or soft-launched applications.
- McKinsey estimates the size of the prize as being between $200 billion and $340 billion in new value creation every year in global banking. Over 70% to 80% of this resides within fewer than ten areas. These include customer care, credit underwriting, and software engineering.
- Smart banks skip the multi-year core replacement. They add governed middleware on top of the CRM and contact center software they already own.
- Midsize banks have also raised their AI cybersecurity budgets by 31% to protect customer data and meet regulations.
Need a practical 180-day plan? See our guide on AI implementation roadmaps in banking.
Top Generative AI Banking Use Cases
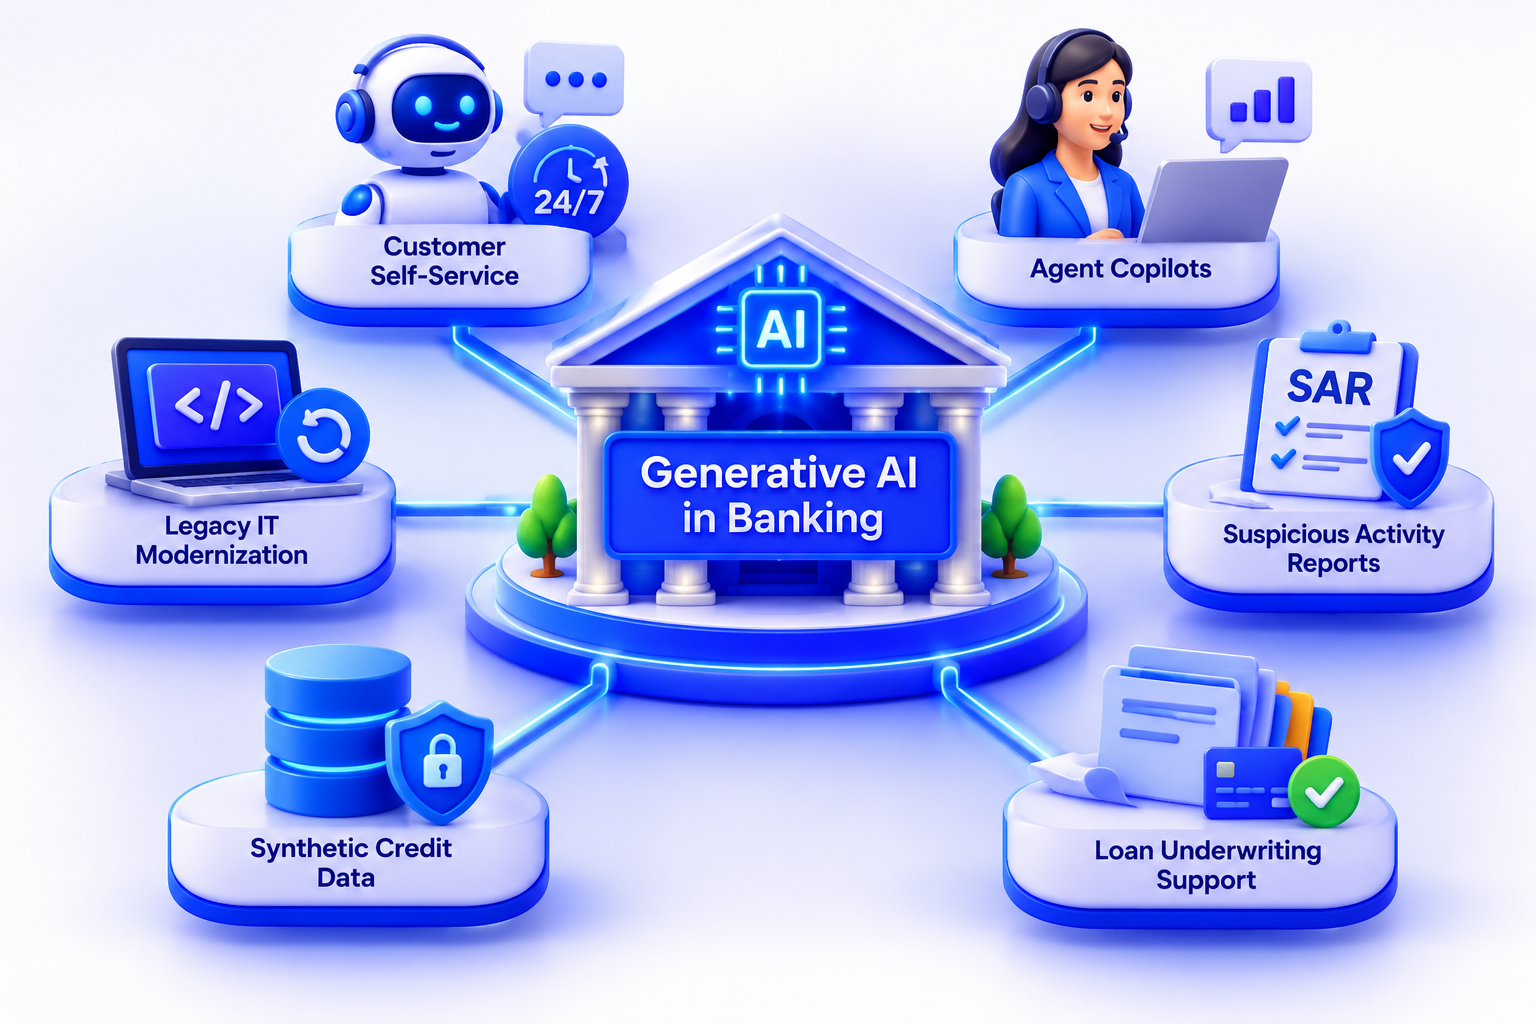
Some major banks have applied generative AI to banking through multiple teams, mainly for the purpose of eliminating bottlenecks and improving service quality.
1. 24/7 Intelligent Customer Self-Service
- The banks use advanced AI chatbots for banking to answer the tier 1 questions on their websites, mobile phones, and even over the phone.
- The chatbots do balance inquiry, cleared check inquiry, charge dispute, and travel notices.
- They remember the conversation across channels, too. Nobody has to repeat account details just because they moved from chat to phone.
2. Real-Time Frontline Agent Copilots
- Plenty of banks use conversational AI for banks to back up agents on tough calls.
- The software transcribes speech, reads the caller’s mood, and pulls up the right guidelines.
- Suggested answers appear on the agent’s screen. When the call ends, it writes the notes and logs the ticket in Salesforce or ServiceNow within 0.8 seconds.
3. Automated Suspicious Activity Reports (SAR)
- The compliance teams can use the generative AI in banks to create summaries of transaction logs and generate SARs.
- A monitoring tool flags possible money laundering.
- The engine then gathers the ledger entries, notes the customer’s patterns, and drafts a standard regulatory narrative.
- Officers still review every report. The drafting time, though, shrinks a lot.
4. Commercial Loan Underwriting Support
- Lending teams pull data from tax forms, operating statements, and personal balance sheets.
- The platform works out debt service coverage ratios and spots missing documents.
- It even drafts early credit memos for underwriters.
- Loans get packaged faster. Risk standards stay strict.
5. Synthetic Credit Data Generation
- Risk teams use generative AI in banking to build synthetic financial profiles.
- They match real portfolio patterns without exposing one real customer.
- Credit models can be rigorously tested by developers and analysts while running simulations on economic recessions without violating stringent privacy regulations.
6. Legacy IT Code Modernization
- Many core systems still run on decades-old COBOL, and it’s expensive to maintain too.
- Generative coding tools read the old codebase and document its logic.
- Then they translate old routines into Java or Python.
- IT teams modernize without painful outages.
Risks and Challenges of Generative AI in Banking
No honest guide skips the downsides. Using generative AI in banking comes with real risks, and leaders can’t wave them away.
Hallucinations take precedence. Language-based models create content based on probability rather than facts. Thus, an ungrounded language model may generate incorrect fees or even incorrect credit policies. This will pose legal problems and irate clients in the regulated world.
Finally, privacy and data residency require strong guardrails too. There are regulations such as GDPR and CCPA limiting which types of customer data can be shared by the foundation model providers with other organizations. Therefore, banks have to ensure zero data-sharing agreements.
Last, regulators want explainable decisions. Lending rules say a bank must document why it denied an applicant. Build clear audit trails. Cite internal policy sources. Let licensed underwriters make the final call. For more on governed workflows, read our overview of conversational AI in financial services.
How to Choose a Generative AI Platform for Your Bank
Choosing a platform for generative AI in banking revolves around three factors. These include security, deployment speed, and governance design.
- Skip generic chat tools that can’t check their own answers. A good platform spots conflicting facts across policy files, procedures, and product guides.
- Thunai Brain turns enterprise documents into structured knowledge graphs, removes outdated rules, and cuts hallucinations by 95%. See how top firms organize scattered data in our Thunai Brain customer support knowledge base case study.
- Speed matters just as much. Long custom projects that replace core mainframes often fail once complexity piles up.
- Successful deployment of generative AI in the banking industry relies on non-invasive middleware that integrates with contact center software such as Genesys, Avaya, and Cisco and CRM systems like Salesforce and ServiceNow.Thunai offers prebuilt financial workflows that launch in under 48 hours, with no engineering delays.
- The platform must also get the task done, not just talk about it. The platform needs to process card replacements, collect the KYC documentation, update the records, and close tickets within one second.
- Our review of modern customer experience platforms shows how unified setups smooth these steps.
- Don’t just take our word for it. On Product Hunt, customer operations leaders call Thunai a second brain that unifies scattered knowledge and keeps replies accurate. Across enterprise software review sites, it holds a 4.8 out of 5 rating.
- Community banks, regional banks, and credit unions see up to an 80% deflection rate and a 66% reduction in handle time. They also see an 85% first contact resolution rate and a 26% increase in Net Promoter Score.
Ready to modernize your contact center? Deploy specialized AI agents for banking and finance for secure, governed productivity. Book a demo today and watch governed agentic workflows in action.
FAQ
What is generative AI in banking?
Generative AI in banking is a set of deep learning systems and large language models. They study a bank’s financial data to create original content, resolve service requests, draft regulatory reports, and run actions across core systems.
Is customer financial data safe when using AI?
Yes, if the platform follows rules. The security system keeps no data hides info automatically gives access only to the right people and can run in a private cloud or, on your own servers. The enterprise system has been. Approved by SOC 2 Type II, ISO 27001 and ISO 42001.
How fast can banks deploy generative AI solutions?
In-house builds can take 6 to 12 months. Specialized agentic platforms deploy in under 48 hours. Systems like Thunai act as governed middleware. They connect to your current CRM and contact center software through APIs, so core banking mainframes stay untouched.
Can generative AI in banking reduce contact center operating costs?
Yes. Banks reach up to an 80% Tier 1 deflection rate on routine questions across phone, chat, and email. Live agent copilots cut Average Handle Time by 42% to 66% and cut customer escalations by 70%. They also write post-call notes in 0.8 seconds, which adds up to real savings in operating expenses.